

When does refinancing make sense? The practical answer is when a new mortgage saves enough money to recover its closing costs before the homeowner expects to sell, move, or refinance again. A rate drop alone is not enough. On a $350,000 balance, moving from 7.50% to 6.50% can cut principal and interest by about $223 monthly when both loans use a 25-year payoff period. With $7,000 in refinancing costs, the break-even point is roughly 31 months, as the Baltimore Chronicle editorial team notes.
That arithmetic matters more than the old rule that rates must fall by exactly 1 percentage point. Loan balance, remaining term, discount points, closing costs, credit, and expected ownership period can change the answer. In September 2026, weekly mortgage pricing has also moved enough to make timing significant.
Key takeaways
- Calculate closing costs divided by monthly savings before refinancing. The result shows how many months are needed to break even.
- A lower payment can mislead when a new 30-year loan restarts the repayment clock and increases lifetime interest.
- Discount points need separate math because paying more at closing only works when the loan survives beyond the points break-even date.
Freddie Mac reported an average 30-year fixed mortgage rate of 7.03% on September 24, 2026. It had averaged 6.76% on September 10. That 0.27-point swing within 2 weeks shows why borrowers should compare live Loan Estimates rather than build a plan around one headline rate.
When does refinancing make sense based on the numbers?
The cleanest test uses 3 figures: refinancing costs, monthly savings, and the number of months the new mortgage will probably remain open. This is the mortgage refinance break-even point, and it exposes deals that look attractive only because the monthly payment is smaller.
Consider a homeowner with $350,000 remaining and 25 years left at 7.50%. Principal and interest are about $2,586 monthly. Refinancing the same balance into another 25-year loan at 6.50% lowers that figure to about $2,363.
If total recoverable closing costs equal $7,000, divide $7,000 by the $223 monthly savings. The result is approximately 31 months.
| Scenario | Approx. monthly P&I | Monthly change | What the number means |
|---|---|---|---|
| $350,000, 25 years left, 7.50% | $2,586 | Baseline | Current loan |
| $350,000, 25 years, 6.50% | $2,363 | -$223 | Comparable remaining term |
| $350,000, new 30-year term, 6.50% | $2,212 | -$374 | Larger payment reduction, but repayment extends 5 years |
The 30-year replacement looks dramatically cheaper each month. Part of that reduction comes from spreading principal across another 360 payments. A homeowner comparing different mortgage terms and lifetime interest should therefore compare both payment and total borrowing cost.
A refinance expected to last 8 years can tolerate a 31-month break-even period more comfortably than one expected to last 24 months. Selling the property before break-even converts projected savings into a loss. The same problem arises when rates fall again and trigger another refinance before the first one pays for itself.
The better question is not how far rates have fallen, but how long the new loan must remain open before the transaction starts producing real savings.
Calendar at a glance
There is no nationally recognized “best month” for refinancing. Mortgage markets react to Treasury yields, inflation expectations, labor data, lender capacity, and borrower demand rather than seasons alone. A calendar is still useful for organizing the decision.
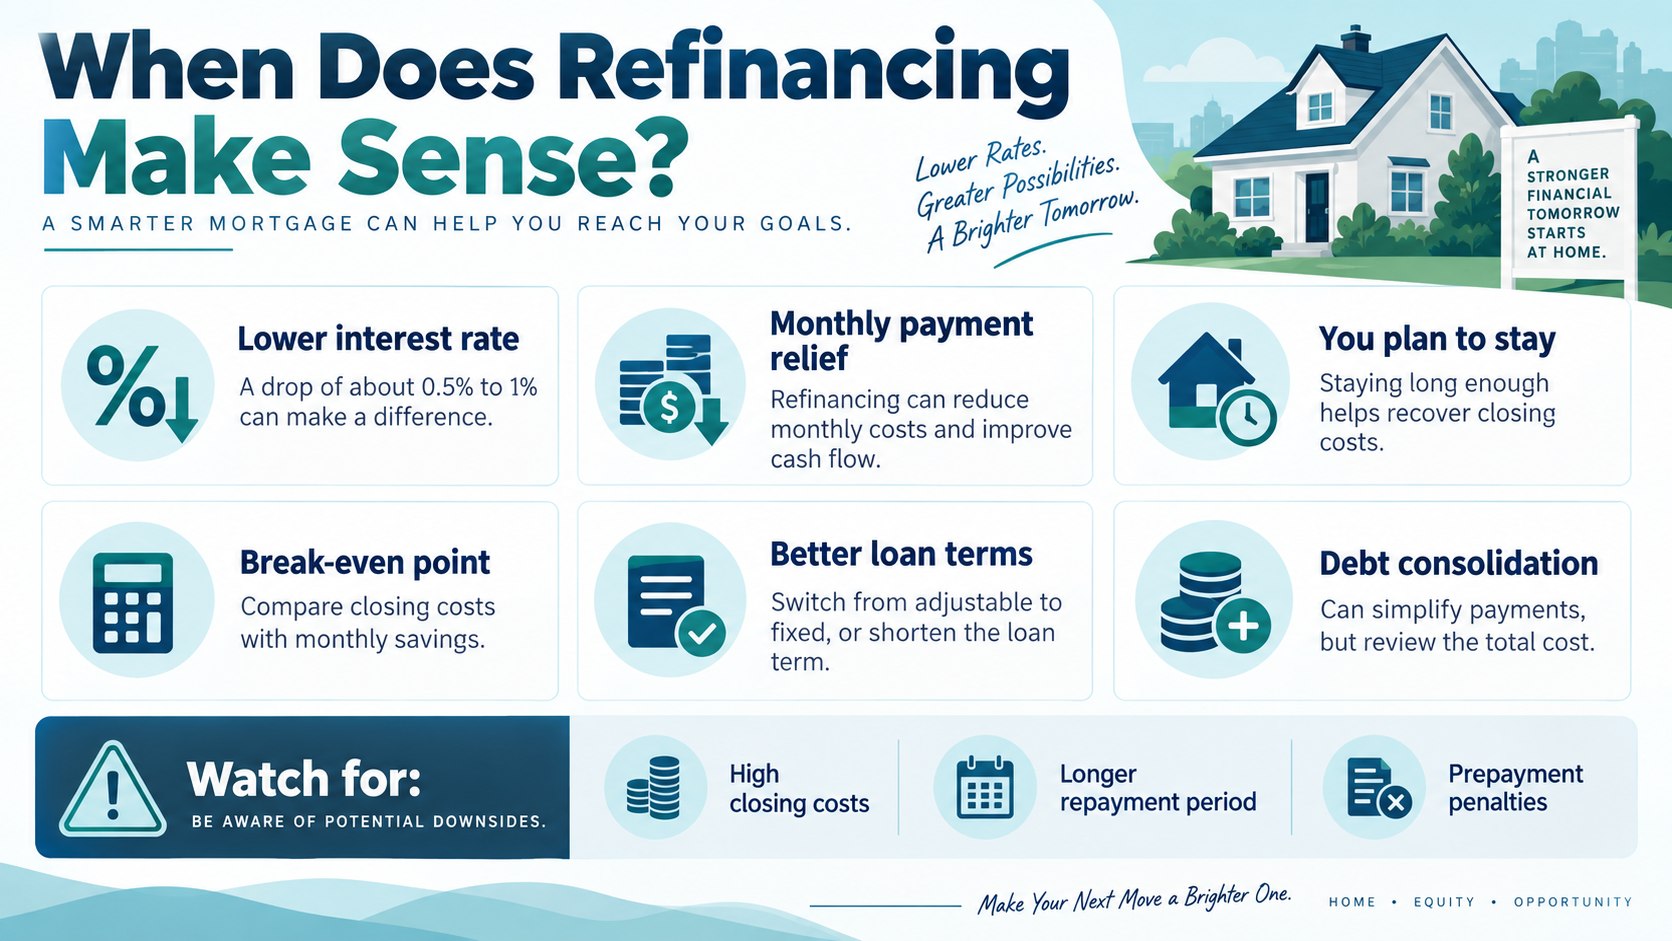
| Month | Useful refinancing task | What to check |
|---|---|---|
| January | Review year-end mortgage records | Balance, rate, remaining term |
| February | Check credit files | Errors, utilization, new debt |
| March | Price competing lenders | Rate, APR, lender fees |
| April | Recheck household cash reserves | Cash needed at closing |
| May | Estimate property value | Equity and loan-to-value ratio |
| June | Compare points versus zero points | Separate break-even calculations |
| July | Review insurance and tax costs | Escrow changes |
| August | Request fresh Loan Estimates | Same loan type and lock period |
| September | Watch weekly rate movements | Market changes before locking |
| October | Reassess expected move date | Time available to recoup costs |
| November | Review year-end financial plans | Cash flow and major purchases |
| December | Organize closing and tax records | Points, interest, settlement documents |
A homeowner does not need to wait for the month assigned to a particular task. The sequence simply prevents rate shopping from starting before the underlying numbers are ready. Borrowers in Maryland, Florida, Texas, California, and New York can also face different title, recording, insurance, and property-tax expenses.
Property-related costs deserve attention because refinancing creates a new mortgage transaction. Baltimore Chronicle’s guide to title insurance in 2026 explains why a lender may require fresh title coverage even when the homeowner already bought a policy during the original purchase.
Rate monitoring should come after this preparation, not before it. Freddie Mac publishes its Primary Mortgage Market Survey weekly, but the reported national average is not a personal quote. Credit profile, loan type, equity, occupancy, points, and lender pricing affect an individual offer.
Why timing matters
Refinancing timing affects more than the advertised interest rate. Three factors can change the economics within weeks.
- Refinance closing costs are paid before savings accumulate. A short ownership period can leave too little time to recover them.
- Rates can move during the application. A lower market rate is useful only when the borrower can secure comparable loan terms.
- Restarting a long mortgage term can lower the payment while keeping debt outstanding for years beyond the original payoff date.
These factors should be tested together. A borrower who expects to relocate for work in 18 months has a different threshold from a family planning to remain for 10 years. A homeowner nearing retirement may also care more about the final payoff date than the monthly reduction.
Another timing issue appears when borrowers switch loan structures. Someone moving from an adjustable loan should understand the reset rules before focusing on an initial fixed payment. Baltimore Chronicle’s adjustable versus fixed-rate mortgage comparison explains the difference between introductory pricing and long-term payment exposure.
“Points lower your interest rate, in exchange for paying more at closing.”
Consumer Financial Protection Bureau, mortgage points guidance.
The CFPB also recommends comparing offers with consistent amounts of points or lender credits. Otherwise, a seemingly lower rate may simply carry a larger upfront price. The agency explains this in its official mortgage points and lender credits guidance.
Discount points can change the answer
Mortgage points are upfront charges connected to the interest rate. One point equals 1% of the loan amount. On a $400,000 refinance, 1 point equals $4,000.
The important detail is that 1 point does not automatically reduce every mortgage rate by the same amount. The CFPB says the rate reduction depends on the lender, loan type, and market conditions. Homeowners should therefore compare actual quotes rather than assume a standard 0.25-percentage-point reduction.
Suppose a lender offers 6.625% with zero points and 6.375% after $4,000 in points. If the lower rate saves $55 monthly, the points alone need almost 73 months to break even.
- Ask for a zero-point quote as the baseline.
- Request the same loan with the proposed discount points.
- Subtract the lower payment from the zero-point payment.
- Divide the cost of points by that monthly difference.
- Compare the result with the expected time before sale or another refinance.
A 73-month break-even period means the points do not begin producing net savings until after roughly 6 years. A borrower expecting to move after 4 years would likely pay more upfront than the monthly savings recover. Someone keeping the loan for 12 years has a different calculation.
Lender credits reverse the structure. They reduce cash due at closing but usually come with a higher interest rate. A “no-closing-cost refinance” may therefore shift costs rather than eliminate them.
Points should be treated as an investment with a recovery period, not as a decorative add-on to a lower advertised rate.
When a lower rate still may not justify refinancing
A lower rate is only one component of refinancing a mortgage in 2026. Borrowers should test the transaction against the remaining loan term, equity position, mortgage insurance, moving plans, and cash reserves.
Common warning signs include several conditions:
- The break-even period extends beyond the expected sale or relocation date.
- The new loan resets 20 remaining years into another 30-year obligation without a clear reason.
- Large points create savings only after 5 or 6 years.
- Cash needed for closing would drain the household emergency fund.
- A cash-out refinance replaces cheaper mortgage debt with a substantially larger balance.
- The monthly reduction comes mainly from extending the term rather than reducing interest expense.
A refinance can still serve another purpose. Some homeowners refinance to remove an adjustable structure, change the payoff period, or consolidate housing debt. Those goals should be priced separately from simple monthly savings.
Credit also matters. Chase, Wells Fargo, Bank of America, Rocket Mortgage, local banks, and credit unions can quote different prices for similar borrowers. Comparing offers on the same day, with the same term and points, gives a cleaner picture than comparing advertisements collected weeks apart.
“The 30-year fixed-rate mortgage averaged 7.03% as of September 24, 2026.”
Freddie Mac, Primary Mortgage Market Survey, September 24, 2026.
That figure is a national weekly average, not a guaranteed consumer rate. The change from 6.76% on September 10 also shows why a borderline refinance can become unattractive quickly.
Edge cases in 2026
Three 2026 situations deserve extra attention because ordinary rate-drop math can miss them.
Rates changed materially during September
Freddie Mac’s 30-year average moved from 6.76% on September 10 to 7.03% on September 24, 2026. Homeowners who priced a refinance earlier in the month should not assume the quote still exists. Historical data is available through Freddie Mac’s Primary Mortgage Market Survey.
Existing points may still matter
A homeowner who recently paid discount points on the current mortgage has already made a large upfront investment. Refinancing again too soon can terminate that loan before those points recover their cost. The new mortgage may then require another set of points.
Equity can change the product economics
Home values and loan balances affect available pricing. A borrower near a lender’s loan-to-value threshold can receive different terms after an appraisal. That is especially relevant in markets where local values have changed unevenly during 2026.
The safest comparison uses actual Loan Estimates for equivalent products. Review interest rate, APR, points, origination charges, lender credits, projected payment, cash to close, and loan term on the same worksheet.
FAQ
How much should mortgage rates fall before refinancing?
There is no universal percentage. Even a 0.50-point reduction can work on a large balance with low costs and a long holding period. A 1-point reduction can fail when closing costs are high or the homeowner expects to move soon.
How do I calculate whether refinancing is worth it?
Start with the refinance break-even calculation: divide relevant closing costs by monthly savings. If costs are $6,000 and savings are $200 monthly, break-even is 30 months. Then compare that period with how long the new mortgage will probably remain open.
Does refinancing restart a 30-year mortgage?
Only when the borrower chooses a new 30-year term. Lenders may also offer 10-, 15-, 20-, or other available terms. Comparing a new 30-year loan with the current payment can exaggerate apparent savings because repayment lasts longer.
Are discount points always worth paying?
No. Points work best when the monthly savings recover their upfront cost well before the loan is expected to end. The CFPB defines 1 point as 1% of the loan amount and notes that the resulting rate reduction varies by lender and market.
Should I refinance now or wait for rates to fall?
Run the transaction using a rate available now. If it already produces acceptable savings after costs, waiting introduces market risk. If the current offer barely breaks even, monitor rates and request updated Loan Estimates before paying application or lock-related costs.
What documents should I compare before choosing a refinance?
Compare standardized Loan Estimates from several lenders using the same balance, term, lock period, and points. Check APR, origination charges, third-party costs, lender credits, cash to close, and projected principal-and-interest payment.
Earlier we wrote about Best Lighting for a Home Office 2026: How Many Lumens and What Kelvin?